

At MS Realty, we work with NRI families investing in Santacruz and BKC every month, and the questions we field are almost always the same — what can I legally buy, how do I pay for it from abroad, and what happens if I can't be in Mumbai for registration. This guide walks through all three.
Can NRIs Legally Buy Property in Mumbai?
Yes. Under the NRI property purchase rules laid out by the Foreign Exchange Management Act (FEMA), Non-Resident Indians and Overseas Citizens of India can buy both residential and commercial property in India — including Mumbai — without seeking prior approval from the Reserve Bank of India. This is the starting point for any NRI property buying guide Mumbai buyers rely on: the legal door is already open.
There is one hard restriction: NRIs cannot purchase agricultural land, plantation property, or farmhouses. These can only be acquired through inheritance, not direct purchase. Everything else — flats, apartments, offices, retail shops — is fair game, provided the transaction is funded correctly.
Step-by-Step Process to Buy Property in Mumbai as an NRI
- Define your budget and purpose — self-use, rental income, or long-term appreciation. This shapes which locality suits you; see our comparison of the best areas for NRI investment in Mumbai.
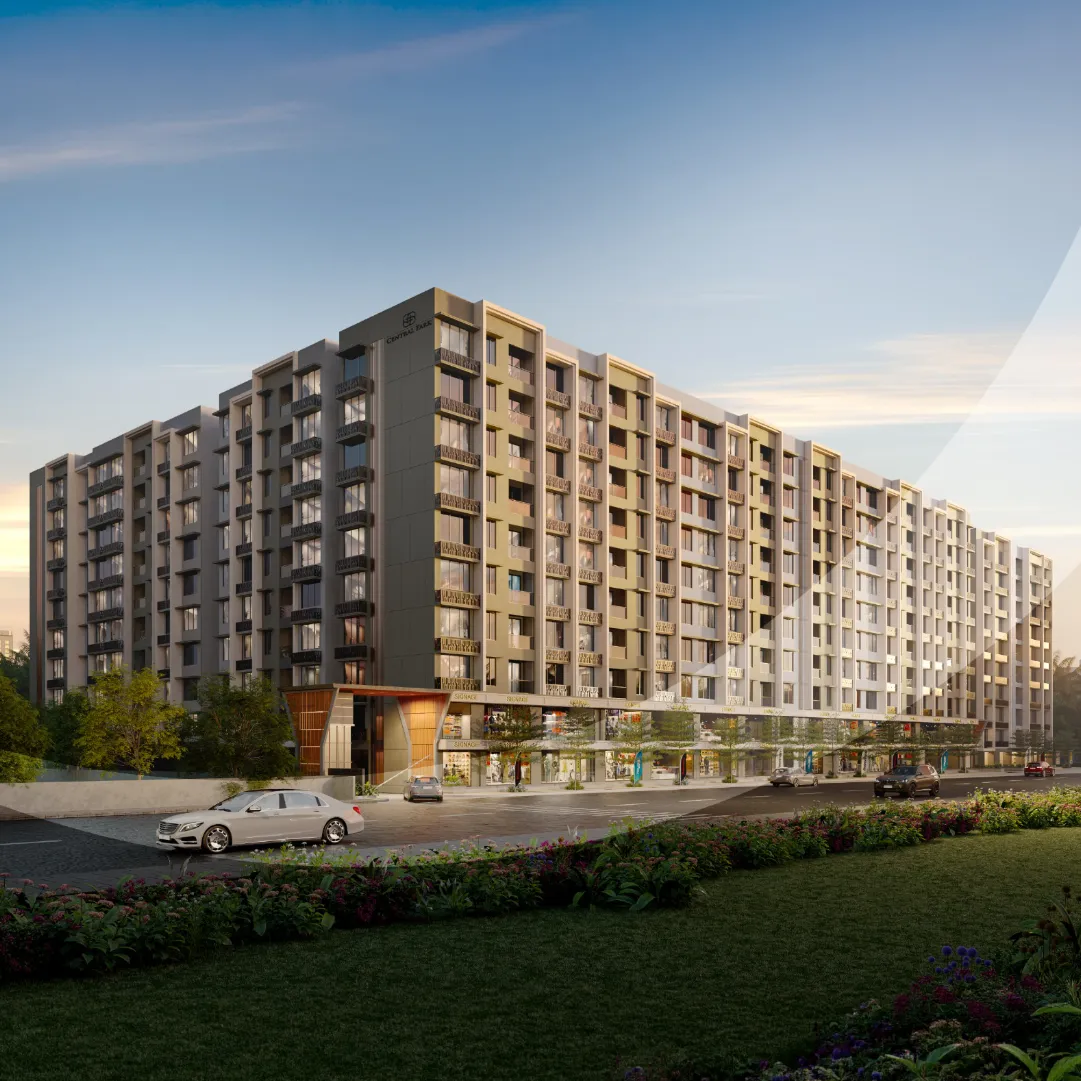
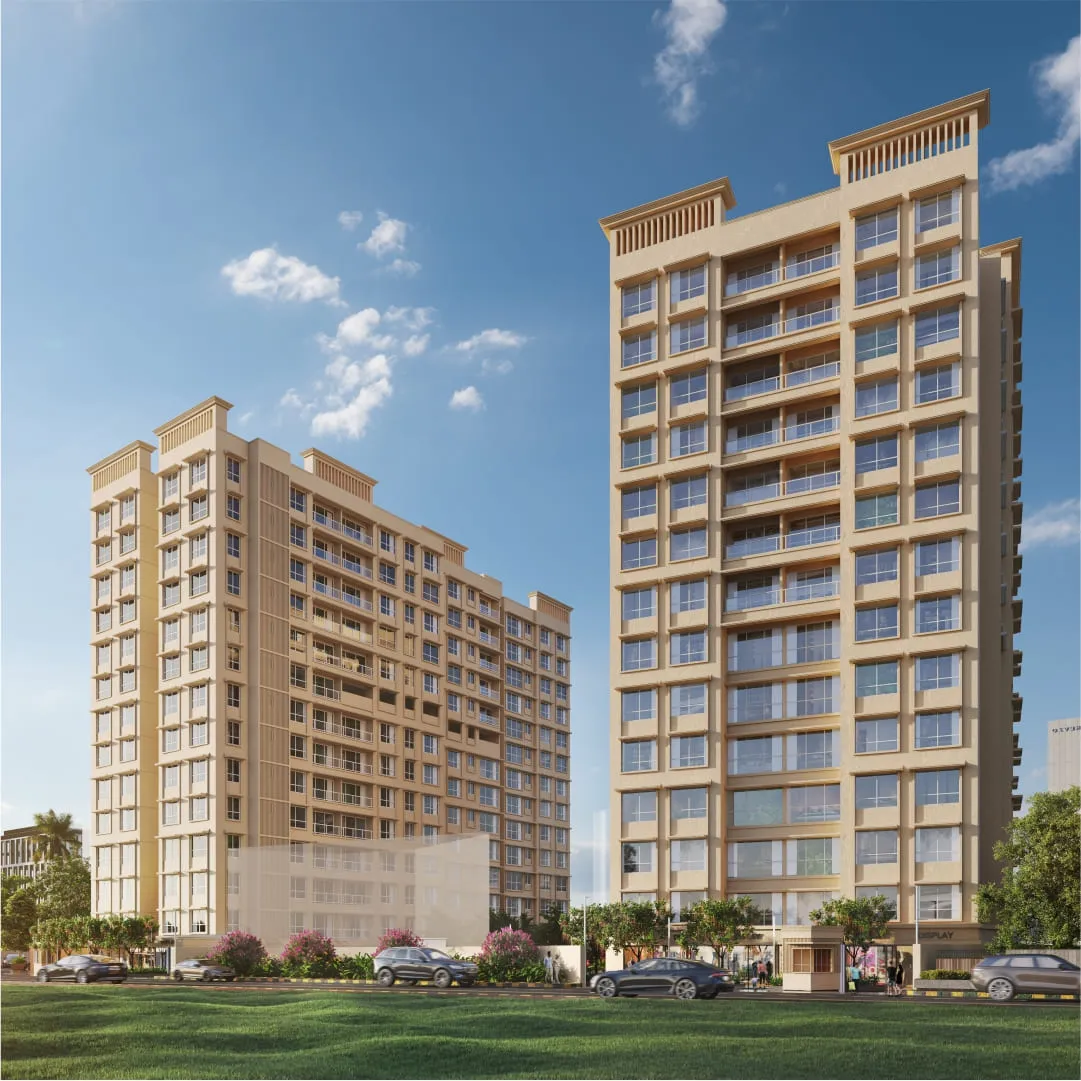
- Shortlist RERA-registered projects only. Every MS Realty development — including Courtyard and Gateway in Santacruz, and Central Park in Kalina — is RERA-registered; you can verify the registration number on each project page before booking anywhere.
- Verify the property title, encumbrance certificate, and approvals (IOD, CC, OC) — either yourself through a lawyer or via the developer's legal team.
- Sign the Agreement for Sale, which sets out the payment schedule, possession date, and penalty clauses.
- Arrange financing if needed. NRI home loans in Mumbai typically cover 75–90% of the property value — see our full breakdown of NRI home loan eligibility and rates.
- Make payments strictly through your NRE, NRO, or FCNR account — never in cash or foreign currency directly.
- Register the property at the local sub-registrar's office and pay applicable stamp duty and registration charges.
- Complete post-purchase compliance: rental agreement registration (if letting it out), and annual income tax filing on any rental income earned in India.
Documents Required for NRI to Buy Property in India
| Document | Why it's needed |
|---|---|
| PAN card | Mandatory for any property transaction and for tax filing |
| Passport and visa / OCI or PIO card | Establishes NRI/OCI status |
| Overseas and Indian address proof | KYC requirement at registration and for the bank |
| Power of Attorney (if applicable) | Required if you cannot be physically present for registration |
| Passport-size photographs | Standard registration requirement |
| Income proof / bank statements | Needed only if you're financing the purchase with a home loan |
Payment Rules: NRE, NRO Accounts and TDS
All payments must be routed through banking channels — your NRE, NRO, or FCNR account, or via an inward remittance through normal banking channels. Cash, traveller's cheques, and direct foreign currency payments are not permitted under FEMA.
TDS is where many NRIs get caught out. If you're buying from a resident Indian and the property value exceeds ₹50 lakh, you must deduct 1% TDS before paying the seller and deposit it with the Income Tax Department. If you're buying from another NRI seller, the TDS rate is significantly higher — often 20%+ plus applicable surcharge and cess. Always confirm the exact TDS rate with a chartered accountant before finalising the payment schedule.
Power of Attorney for NRI Property Purchase
If you can't travel to Mumbai for registration, you can execute the purchase through a Power of Attorney for NRI property purchase. The POA must be signed, notarised, and either attested by the Indian consulate in your country of residence or apostilled (for Hague Convention countries), then registered with the sub-registrar in Maharashtra. Several of our own NRI buyers at Courtyard and Gateway have completed their entire purchase this way, coordinating remotely with our sales team — an improperly executed POA is one of the most common reasons NRI property deals run into trouble later, so it's worth getting right the first time.
Repatriation Rules: Taking Sale Proceeds Back Abroad
When you eventually sell, you can repatriate sale proceeds up to USD 1 million per financial year, for up to two residential properties, through an Authorised Dealer bank. Before repatriating, you must clear all applicable capital gains tax and obtain a Chartered Accountant's certificate (Form 15CB) along with Form 15CA filed with the Income Tax Department.
Common Mistakes NRIs Make When Buying Property in Mumbai
- Not verifying RERA registration before booking a unit
- Paying through unauthorised channels (cash, foreign wire outside banking norms)
- Executing an invalid or unregistered Power of Attorney
- Skipping independent legal due diligence on title and encumbrances
- Underestimating the total cost — stamp duty, registration, and GST add 6–11% on top of the property rates in Mumbai
How MS Realty Supports NRI Buyers
Buying from abroad shouldn't mean buying blind. Our team regularly works with NRI clients on documentation, POA coordination, and remote registration for our Santacruz and Kalina developments. If you'd like to talk through a purchase before you commit, get in touch with our sales team or browse our current projects.